
Your Rights When Denied Insurance Coverage
November 2, 2026 | Firm Name | Blog

Last Updated: November 2, 2026
Quick Summary
If you receive denied insurance coverage, you have the right to appeal the decision, first through an internal appeal reviewed by the insurer and then, if that fails, through external review by an independent organization. Your denial notice must state the reason, the plan rule relied on, and your appeal deadline and options.
- Read your denial notice for the reason code, deadline, and appeal address, and mark them immediately.
- Internal appeal deadlines are commonly at least 180 days for job-based and marketplace plans.
- External review is commonly available for four months after a final internal denial.
- Skipping the internal appeal or missing its deadline can forfeit your external review right entirely.
- Expedited appeals may apply when your doctor certifies that waiting could seriously jeopardize your health.
Table of Contents
- What a Denial Notice Actually Tells You
- Health Insurance Claim Denied: What Next?
- How to Successfully Appeal an Insurance Denial
- When Your Claim Is Denied as Not Medically Necessary
- Health Insurance Claim Denied but I Owe Nothing: Sorting Out the Bill
- Deadlines, Documents, and What Happens While You Wait
- How Your Accident Report Supports a Denied Coverage Appeal
- Request Your Free Accident Report Before You Appeal
- Frequently Asked Questions
What a Denial Notice Actually Tells You
To get your FREE accident report please fill out the yellow form.
A denial notice is a written explanation from your insurer stating why it will not pay for a claim or service. It is not the final word.
The notice usually names three things: the reason for the denial, the plan rule it relies on, and your appeal options. Read it with a highlighter in hand. Mark the reason code, the deadline, and the address for appeals.
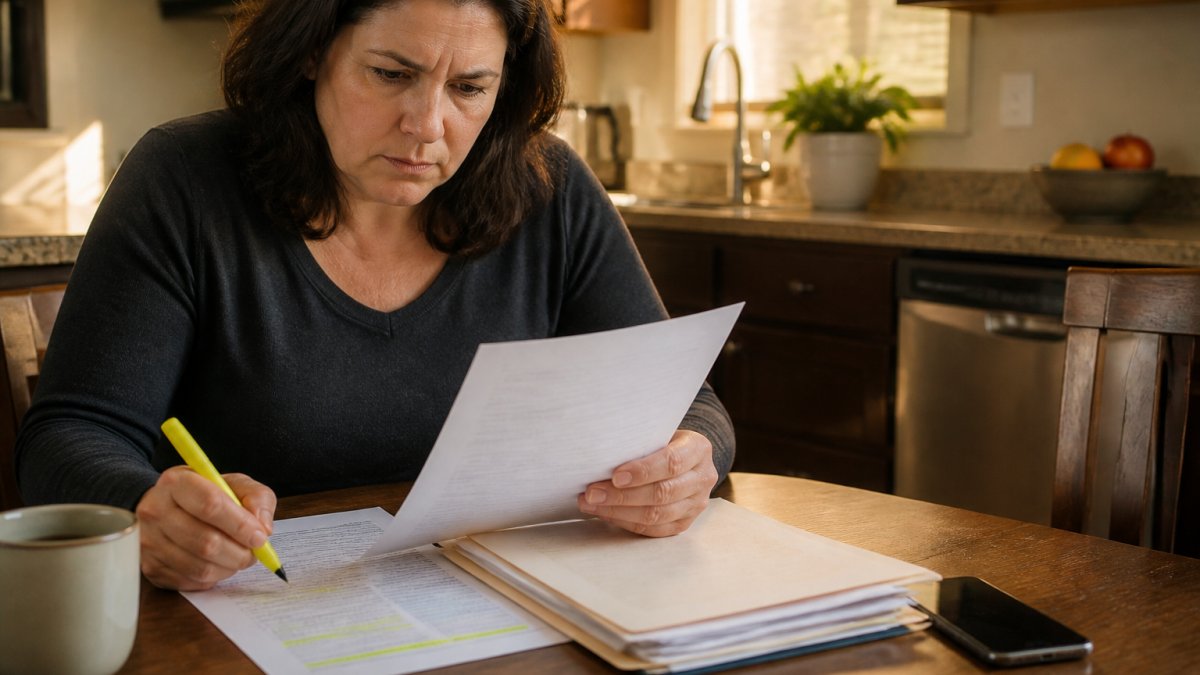
Most people skim these letters and miss the deadline. The Consumer Appeal Rights in Private Health Coverage guidance explains that your notice must spell out both your internal appeal rights and, in some cases, your right to independent review.
Your explanation of benefits is a related document. It shows what the insurer paid, what it denied, and what it says you owe. Keep every copy.
Health Insurance Claim Denied: What Next?
Start by confirming the reason. Then check your deadline. Then decide which appeal route fits.
A denied insurance coverage decision falls into a few common buckets:
- Medical necessity: the insurer says the care was not needed.
- Prior authorization: you or your provider skipped approval.
- Coding or processing error: a wrong code or missing detail.
- Out-of-network: the provider was outside your plan.
The reason drives your next move. A processing error may be fixed with a resubmitted claim. A medical necessity denial needs clinical evidence.
If you are unsure how to file the underlying claim correctly, our guide on how to file an insurance claim walks through documentation and denials step by step.
How to Successfully Appeal an Insurance Denial
You appeal by submitting a written appeal with supporting documentation before your deadline. Most successful appeals share one trait: they answer the exact reason stated in the denial notice, using the plan’s own criteria and your clinician’s records.
Before you write anything, sort the denial into the right lane. The appeal route, the deadline, and the reviewer all depend on which of these you are facing:
- Claim-processing error (wrong code, missing modifier, duplicate submission): often resolved by asking the provider to resubmit a corrected claim rather than filing a formal appeal. Confirm with the billing office first.
- Coverage dispute (service excluded, out-of-network, benefit limit): an appeal that cites the plan document’s language and any applicable exception.
- Medical necessity denial: an appeal built on clinical evidence and the plan’s own review criteria.
- Eligibility or termination issue: usually resolved by proving enrollment dates or coordination of benefits, not by clinical argument.
Internal Appeal: The First Step
An internal appeal is reviewed by the insurer itself. Federal internal claims and appeals rules set the filing window and decision timelines for many plans, and your denial notice should state the exact deadline.
Ask for the plan’s clinical review criteria and the specific plan provision relied on. Those two documents tell you what evidence will actually move the reviewer.
External Review: When the Insurer Says No Again
If the internal appeal is denied (or the plan misses its decision deadline), you may have a right to external review by an independent review organization. Under the federal external review process, a deadline applies to request it after the final internal denial, and not every denial qualifies.
Watch out: if you skip the internal appeal or miss its deadline, you can lose the external review right entirely, the two stages are linked.
How the Rules Change by Plan Type
The protections above are not uniform. Where you verify your rights depends on what kind of plan you have:
- Employer-sponsored and marketplace plans: generally subject to the federal internal claims and appeals and external review rules; state insurance departments handle consumer complaints for fully insured plans.
- Self-funded employer plans: federal ERISA rules apply, but state external review laws generally do not, the federal process is the path.
- Medicare Advantage and Part D: use the plan’s reconsideration process, then the Independent Review Entity, then further levels; deadlines and forms differ from commercial plans.
- Medicaid managed care: state-specific appeal and fair-hearing rules apply, and your state Medicaid agency is the place to confirm them.
If you are unsure which category you fall into, check your plan document or call the member services number on your ID card and ask, in writing, which appeal process and deadline apply.
Expedited Appeals
If your doctor certifies that waiting for a standard decision could seriously jeopardize your health, you can request an expedited appeal. Urgent appeals are decided on a faster timeline than standard appeals; confirm the exact decision window in your plan documents. Ask your clinician to put the urgency statement in writing and submit it with the appeal.
If you want a clean walkthrough of the filing side, see steps to file an insurance claim.
When Your Claim Is Denied as Not Medically Necessary
A medical necessity denial means the insurer decided the care was not covered under its clinical rules.
Your strongest tool is your doctor’s records. Ask for the clinical notes, test results, and a short letter explaining why the service was needed.
A 2026 survey from the American Hospital Association found that 41% of people who experienced a prior authorization denial said it delayed medical care, and 28% said a health issue resulted.
For accident-related care, medical records for car accident claims explains how to collect the records that support this kind of appeal.
Request a copy of your free accident report →
Health Insurance Claim Denied but I Owe Nothing: Sorting Out the Bill
If your claim was denied but you owe nothing, the provider likely wrote off the balance or billed another payer.
Check three things:
- Does the explanation of benefits show a zero patient responsibility?
- Did the provider accept the denial as final?
- Was the claim sent to auto insurance or another policy instead?
Sometimes a denial is simply routed elsewhere. A hospital bill may sit unpaid while your auto medical payments coverage handles it.
The Commonwealth Fund’s 2026 survey found that 43% of adults who experienced a claim denial said it led to medical debt they were still paying off.
Deadlines, Documents, and What Happens While You Wait
Deadlines are the part most people get wrong. Appeal windows run from the date printed on your denial notice, not the date you opened the envelope, and they are shorter than most people expect.
Deadline Tracker
Use a single sheet or note to record each item below. Fill it in the day the notice arrives.
|
Item |
What to Record |
Why It Matters |
|---|---|---|
|
Denial date |
Date printed on the notice |
Starts your clock |
|
Internal appeal deadline |
Date stated on the notice (commonly at least 180 days for job-based and marketplace plans) |
Miss it and you may lose the appeal |
|
External review window |
Commonly four months from the final internal denial |
Second chance, but only if you file in time |
|
Expedited request |
Date you asked for urgent review |
Triggers a 72-hour decision standard |
|
Documents sent |
Records, letter, forms, criteria request |
Proves what you submitted |
|
Submission proof |
Fax confirmation, portal receipt, or certified-mail tracking |
Settles disputes later |
|
Decision due date |
Insurer’s response window |
Tells you when to follow up |
Document Checklist
Gather these before you write the appeal letter:
- The denial notice and the explanation of benefits
- The full plan document and summary plan description
- The plan’s clinical review criteria for the service in question
- Clinical notes, test results, imaging reports, and treatment history
Proof of Submission
Submit by the method the notice requires, and keep proof. If you fax, save the confirmation page. If you use a portal, screenshot the submission receipt. If you mail, use certified mail with return receipt. Keep a copy of everything you sent, dated.
Watch out: a phone call is not a submission. Verbal appeals rarely preserve your deadline, follow up every call in writing.
What Happens While the Appeal Is Pending
For non-emergency services, the plan may pause the service while the appeal is reviewed, and the provider may bill you in the meantime.
Continuation-of-care protections can apply in some situations, for example, when an ongoing course of treatment was already authorized, or during certain transitions in care.
Timing rules vary by claim type. Our breakdown of critical deadlines after a car accident covers the timing that applies to accident-related claims.
How Your Accident Report Supports a Denied Coverage Appeal
An official crash report is evidence. It shows the date, the parties, the responding agency, and how the collision happened.
If your auto claim was denied, the report can answer the exact question the insurer raised. Maybe the denial says the accident was not reported.
Request the report early. Corrections take time, and an appeal deadline will not wait for a records request.
Request Your Free Accident Report Before You Appeal
You can request your official report at no cost through our service. We contact the right agency, confirm the report was filed correctly, and get the document into your hands.
Here is what that gives you:
- A verified report to attach to your appeal
- Confirmation the crash was reported as required
- A clear record of fault and parties
- No hours spent calling departments
If you are still deciding whether you need legal help, requesting the report costs you nothing and commits you to nothing. We can also connect you with car accident and injury lawyers if you want a review of your case.
Frequently Asked Questions
How do you fight an insurance denial?
Start with the denial notice: it must state the reason and your appeal instructions. File an internal appeal in writing before the deadline, including medical records and a letter explaining why the service was covered under your plan. If the internal appeal fails, request an independent external review where your plan allows it. Keep copies of everything you submit. Acting quickly matters, because unresolved denials can lead to medical debt.
Can you appeal a denial for lack of medical necessity?
Yes. A claim denied as not medically necessary is one of the denial types most open to appeal, because the decision turns on clinical evidence. Ask your doctor for a letter of medical necessity and the records that support the treatment, then submit them with your written appeal. Medical necessity denials are often the category eligible for independent external review, but eligibility depends on your plan and the applicable rules. Check your plan documents for the exact route.
Can you owe money if your health insurance claim is denied?
Possibly, but not automatically. If a claim is denied, the provider may bill you for the full amount, which is why you should appeal rather than pay right away. Ask the insurer and provider in writing to hold the bill while the appeal is pending. If the denial is overturned, your normal cost sharing applies instead of the full charge. Document every call and keep proof of submission so you can show the claim is under review.
What should you avoid saying to an insurance company?
Avoid guessing at causes, downplaying your symptoms, or agreeing that a service was optional or experimental. Stick to facts your records support and refer questions about medical necessity to your doctor. Request that all communication happen in writing so nothing is mischaracterized. If your denial stems from a car accident, having the official crash report in hand gives you a verified account of what happened, which is far stronger than a phone description.
A denied claim is a setback, not a closed door. The evidence you gather now decides how the appeal goes. Georgia Accident Report retrieves your official crash report for free, verifies it was filed correctly, and connects you with injury lawyers when you want a second set of eyes. Get started with Georgia Accident Report and appeal with the documentation your insurer cannot ignore.

Request a copy of your free accident report:
"*" indicates required fields